The International Auditing and Assurance Standards Board (IAASB) has released proposed revisions to three International Standards on Auditing (ISAs): ISA 330, The Auditor’s Responses to Assessed Risks; ISA 500, Audit Evidence; and ISA 520, Analytical Procedures.
The proposed revisions, when finalised, will complete an important phase of the IAASB’s decade-long modernisation of the International Standards on Auditing, building on recent revisions, including ISA 315 (Revised 2019), Identifying and Assessing the Risks of Material Misstatement. The proposals further embed, clarify and strengthen a principles-based, risk-based audit framework. The revisions also address the increased use of technology in business, financial reporting, and auditing.
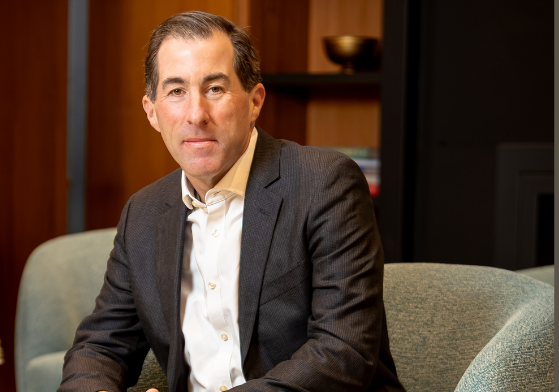
“Over the past decade, the IAASB has modernised the International Standards on Auditing to strengthen audit quality and respond to an evolving environment,” said Tom Seidenstein (pictured), IAASB Chair. “These proposals are an important milestone in that work. With the benefit of stakeholder input and when finalized, the revised standards will further enhance a principles-based, risk-based audit framework that provides a stable foundation for high-quality audits while remaining flexible enough to support innovation as technology continues to evolve.”
The proposed revisions establish a comprehensive basis for auditors’ judgments about audit evidence. They include:
- A revised definition of audit evidence to reflect today’s digital environment.
- Greater emphasis on the intended purposes of audit procedures.
- Strengthened requirements for evaluating the relevance and reliability of information used as audit evidence.
- Clarification of key concepts.
- Reinforced application of professional scepticism throughout the audit.
The proposals also strengthen auditors’ responses to assessed risks by clarifying the role of tests of controls, substantive procedures, and analytical procedures – promoting more consistent and effective audit responses. The proposals reflect the IAASB’s conclusion that a principles-based rather than technology-specific approach is the best way to maintain robust and relevant standards in the face of rapid technological evolution. They enable innovation while preserving the core principles of high-quality auditing. In addition, the proposals include guidance to help auditors exercise professional judgment about appropriate use of technology.
Additionally, the proposed revisions improve the alignment of concepts and principles across the auditor’s risk assessment, responses to assessed risks, and evaluation of whether sufficient appropriate audit evidence has been obtained.