Matthew Davies explains how to calculate under or over absorption of overheads.
In the CIPFA Management Accounting exam students may be assessed on under or over absorption of overheads. It is an area of management accounting that requires some understanding. In this article, we will look at what causes this and how to calculate under or over absorption.
To understand under or over-absorption it is necessary to review absorption of overheads. Let us consider an example of an NHS dental practice. How would you determine the cost of a particular type of tooth filling? Whilst the prime costs could readily be calculated by estimating direct materials and direct labour, overheads such as electricity costs cannot be easily attributed to a specific filling. How can the dental practice’s electricity costs and other overheads be absorbed into the cost of a specific filling?
From your studies you will be aware of the need to apportion or allocate estimated overheads into service and production cost centres. Then the service cost centres are apportioned into the production cost centres.
In the example of the dental practice, we can now assume that those processes have been completed and £1m of overheads for a year have been apportioned into the production cost centre entitled dental treatment areas.
Now, that the £1m of estimated overheads need to be apportioned into production using an appropriate overhead absorption rate (OAR). An appropriate method could be clinical hours. This is the total amount of hours the dentists in the practice spend on dental treatment. If the practice had four dentists, each working 48 weeks a year, 38 hours a week, with 75% of their paid time being spent on clinical work, that would equate to an estimated 5,472 clinical hours in total.
The next step is to calculate an OAR by dividing the estimated total overheads by the estimated clinical hours. In this case it would be £1m/5,472 which equals to £182.75 per clinical hour. That means any treatment can be costed by adding the estimated clinical time multiplied by the OAR and adding that to the prime cost. So, if a particular type of filling takes an estimated 20 minutes, the amount of overheads absorbed into the cost of that filling would be £182.75/60 x 20 = £60.92.
So far all these things have been estimates and are usually done at the start of a period. However, like all estimates, it is unlikely that they become realities. For example, the total overheads during the year is unlikely to be exactly £1m and the total number of clinical hours will probably not be exactly 5,472. Thus, at the end of a period, it is essential to compare our estimates with the actuals. Consider the following information using two different outcomes: –
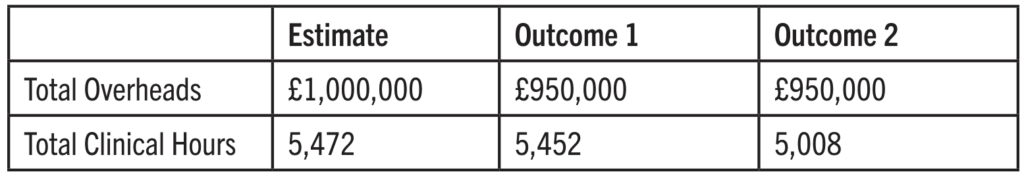
In Outcome 1, some 5,452 clinical hours were worked and £182.75 of overhead costs were absorbed into cost units by a per clinical hour basis, which meant a total of £996,353 (5,452 x £182.75) of overheads were absorbed during the year. However, the actual overheads at the end of the year were £950,000. This meant that £46,353 more overheads were absorbed during the year. This is over absorption.
In Outcome 2, a total 5,008 hours were worked, which resulted in £915,212 of overheads being absorbed, which was £34,788 less than actual overheads. This is under absorption.
In both outcomes, both the total overheads and total clinical hours were less than had been estimated, Outcome 1 resulted in over absorption of £46,353, whereas in Outcome 2 there was an under absorption of £34,788. This example shows that it is not just a case of comparing total overheads. CIPFA students need to learn how to absorb overheads during a period using an estimated OAR and then compare that to the actual overheads incurred. This almost certainly going to result in either an under or over absorption of overheads.
Learning this key area of management accounting will not only help you pass Management Accounting but improve your understanding of the accounting profession..
- Matthew Davies, expert in public sector financial management